
The running costs of a luxury new build home depend on the property and household, but energy performance can make a meaningful difference over time. These figures provide a starting point, not a complete budget for every home.
It is natural to focus on the purchase price when weighing a substantial property investment. But ongoing costs matter too: energy, water, council tax, insurance and internet all contribute to the cost of owning a home.
This article explains how efficiency, maintenance, warranties and purchase price affect ownership costs, and why it helps to consider them over a five- or ten-year period. It also compares new-build and resale homes, helping you assess the full cost of ownership more clearly.
Key Takeaways
- Compare a home’s energy performance and heating system to understand how efficiency may shape bills over time.
- Look beyond the purchase price: project costs can include professional fees, site expenses and items excluded from headline build rates.
- Build a maintenance reserve into your ownership budget, and understand what a new-build warranty covers and for how long.
- Separate household bills from mortgage payments, then account for council tax, insurance, water, internet and any property charges.
Energy efficiency and long-term running costs
Efficiency influences household bills, although both the home’s design and how it is used matter. When assessing the running costs of a luxury new build home, consider energy performance alongside the purchase price.
Efficiency and household energy bills
Energy efficiency describes how well a home retains heat and uses energy for heating, hot water and lighting. A more efficient home may need less energy to maintain comfortable rooms, which can affect household bills.
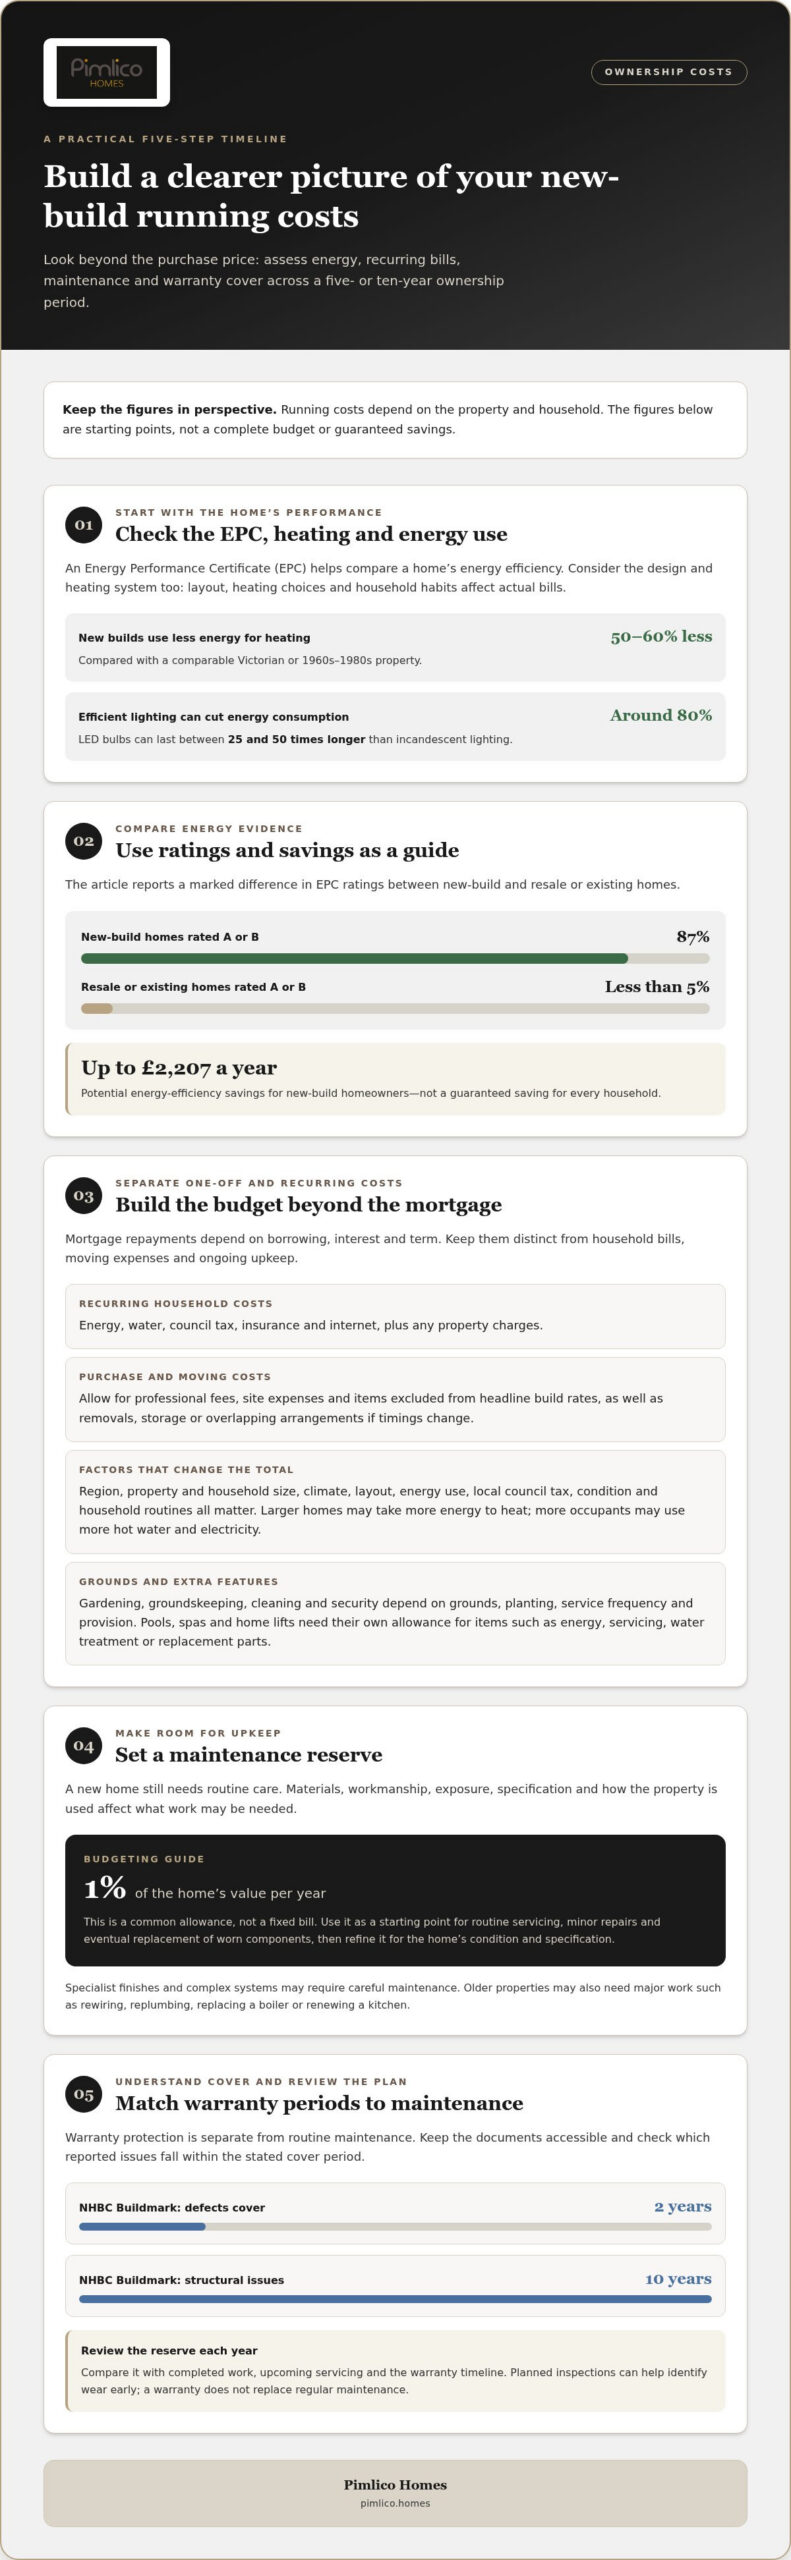
A new build typically uses 50-60% less energy for heating than a comparable Victorian or 1960s-1980s property. Efficient lighting can cut energy consumption by around 80%, while LED bulbs can last between 25 and 50 times longer than incandescent lighting. These details help turn an efficiency rating into a practical budget figure.
EPC ratings and energy efficiency
An Energy Performance Certificate (EPC) gives a property an energy-efficiency rating, making it easier to compare homes. In the UK, 87% of new-build homes have an A or B EPC rating, compared with less than 5% of resale or existing properties.
New-build homeowners could save as much as £2,207 a year through energy efficiency. Treat this as a potential comparison, not a guaranteed saving for every household. Layouts, heating choices and patterns of use affect actual bills, even in a well-designed home.
Energy efficiency may also influence mortgage options, as some lenders offer better rates in certain cases based on a property’s performance. For a bespoke home, consider how the design, heating and infrastructure work together: these choices shape comfort and energy use over time.
The costs of gardening, groundskeeping, cleaning and security depend on the size of the grounds, planting, service frequency and level of provision. Budget for these arrangements alongside energy and council tax.
According to UK Government, councils may allow council tax to be paid in 12 monthly instalments instead of 10.
Site planning can affect how a new build is arranged. According to The National Archives, the Party Wall etc. Act 1996 applies when a new build is constructed within 3 metres of a neighbouring structure, or involves excavation close to a shared boundary.
Costs at different property price points
The purchase price affects borrowing, but it does not determine every annual bill. A larger home may need more heating and upkeep, while local taxes, household routines and the property’s condition also affect ongoing costs. Separate one-off purchase and moving expenses from recurring costs to create a more useful ownership budget.
Running costs vary by UK region, property size and household size. Council tax, climate, layout and energy use all affect the total. More occupants may use more hot water and electricity, while a larger home may take more energy to heat.
Mortgage repayments are a major monthly commitment, determined by borrowing, interest and term. Use a borrowing figure that reflects your likely purchase, then budget separately for household bills and maintenance.
Period properties can have different heating demands. Construction, draughts, glazing and room volumes affect how quickly heat escapes and how long the heating runs. A tall Victorian room, for example, may need a different heating pattern from a compact modern room. These factors can influence the balance between a home’s character and everyday comfort.
Location matters beyond the asking price. Council tax, transport access and local amenities can shape household spending, while demand and condition affect a property’s appeal to future buyers. Compare these factors across locations before deciding that a lower purchase price offers better long-term value.
Moving costs also depend on timing and the property chain. A delayed sale or purchase can affect moving dates and may mean coordinating temporary storage, removals and overlapping household arrangements. Include these practical costs in your purchase budget, rather than treating the mortgage as the only significant figure. Buyers considering a home shaped around long-term ownership can explore design choices for a lasting home.
Maintenance reserves and warranties
Plan for routine care as well as unexpected repairs. A new home still needs upkeep, and specialist finishes or complex systems may require careful maintenance as they age.
A common maintenance allowance is 1% of a home’s value per year. This is a budgeting guide, not a fixed bill: actual work depends on materials, workmanship, exposure and how the property is used. A reserve can help cover routine servicing, minor repairs and eventual replacement of worn components.
Typical annual maintenance and repair costs can be planned using that 1% allowance, then refined around the home’s condition and specification. A bespoke interior with delicate finishes, for example, may need different care from durable surfaces in high-traffic areas.
Warranties provide a separate layer of protection. The NHBC Buildmark warranty covers defects for 2 years and structural issues for 10 years. Luxury new builds include warranties and structural guarantees, but a warranty does not replace regular maintenance. Keep its documents accessible and understand which reported issues fall within the stated cover period.
Distinguish warranty matters from renovation choices. Repainting, refreshing an interior or replacing an electrical appliance may be planned improvements rather than defects. Older properties may also need major work, such as rewiring, replumbing, replacing a boiler or renewing a kitchen. Such projects can substantially change the maintenance budget.
Swimming pools, spas, home lifts and other luxury features have their own upkeep requirements. Annual costs depend on energy use, servicing, water treatment, replacement parts and frequency of use. A pool’s heating and filtration needs, for instance, differ from a lift’s servicing requirements. Give each feature its own budget line rather than including it under general repairs.
Review your reserve each year against completed work, upcoming servicing and the warranty timeline. Planned inspections can help identify wear early, while maintenance and repair records provide a clear history of the home’s care.
There is no single annual figure: a pool or spa’s energy and water-treatment needs differ from a lift’s servicing and replacement-parts requirements, and frequency of use affects costs. Estimate each feature separately when planning upkeep.
Annual running costs of new-build and resale homes
Compare recurring household bills separately from mortgage repayments. Annual totals provide a useful starting point for understanding how property type affects ownership costs.
Water and sewerage bills
Water and sewerage bills cover household water supply and wastewater services. For metered households, usage affects the amount paid. This national household figure is not a specific estimate for a large home.
A larger household, garden watering and frequent use of baths can increase consumption. Water-efficient fittings may reduce metered water use by 15-25% compared with older fittings, so consider taps, showers and toilets when reviewing a property’s likely bills.
Council tax bands for luxury homes
Council tax is an annual household cost determined by a property’s band and local authority. For context, average Band D council tax is £2,065 per year. A luxury home’s purchase price alone does not provide enough information to calculate its council tax.
Compare the band and local charge for each property rather than assuming all high-value homes face the same bill. A person living alone may qualify for a 25% council tax discount. Councils may also allow payment in 12 monthly instalments instead of 10, helping spread the expense.
Both figures exclude rent or mortgage payments and cover energy, water, council tax, insurance and internet. They are useful benchmarks, but actual totals depend on household use and local charges.
Insurance, estate charges and upkeep add further costs. Include garden care, plumbing and lighting in your budget, particularly if a period home needs more attention.
For a considered comparison, explore luxury new-build homes alongside resale options and assess the full annual household budget.
Pimlico Homes: Luxury Detached Homes
Pimlico Homes develops luxury detached homes for buyers weighing design, space and long-term ownership costs. When comparing a new build with a resale property, consider how the home’s layout and features will suit your household over time.
Pimlico Homes also develops executive courtyard homes, bespoke luxury homes and luxury barn conversions. Each offers a distinct approach to living, from a courtyard arrangement to a home shaped around individual preferences or a converted rural building. Your choice of property type helps frame the practical questions in this guide, including energy use, maintenance and household bills.
Explore Pimlico Homes’ properties to find a setting and style that suit your plans. Contact Pimlico Homes to discuss your next step or visit pimlico.homes.
Shape your next move with confidence
Choosing a property involves more than the day you collect the keys. Consider how you want each room to function, which features matter most to your household, and how your priorities might change over time. This turns an ownership budget into a clearer brief for the home itself, helping you weigh lasting comfort against optional additions.
The running costs of a luxury new build home make most sense when considered alongside how you intend to live. Pimlico Homes develops luxury detached homes, executive courtyard homes and bespoke luxury homes, offering distinct approaches to space and design. Each can prompt useful questions about layout, daily use and the details that will make a home feel truly yours.
If you are ready to explore what might suit your plans, contact Pimlico Homes to discuss your plans. A considered next step can bring your priorities into focus and help you move towards a home with confidence.
Frequently Asked Questions
What are the average annual running costs of a luxury new-build home in the UK?
This is a broad benchmark, not a forecast for a luxury home. A larger property with extensive grounds or specialist features needs a separate allowance for maintenance and operation. For a useful comparison, list recurring household bills separately from mortgage payments, planned upkeep and optional amenities.
How much do heating and electricity cost for a large luxury new-build home in the UK?
A large home’s actual heating and electricity use depends on floor area, insulation, heating system, occupancy and chosen temperature. Regularly heating several rooms, for example, differs from using only the main living spaces.
How do energy bills compare for luxury new-build homes with EPC ratings A, B and C?
An EPC rating indicates a home’s energy performance, but it does not determine the household bill. Compare the specific assessment with the heating system, property size and household use to judge likely consumption.
How much does home insurance cost for a high-value new-build property in the UK?
These are broad averages, not a quotation for a high-value property. Rebuilding cost, construction details, location, security and the value of possessions all influence the cover needed. For a luxury home, consider buildings and contents separately, including valuable artwork or furnishings.
What ongoing charges apply to luxury new-build homes, such as estate management fees or service charges?
Charges relate to shared upkeep and property arrangements, so the type of home matters. Check whether your budget also needs separate provision for private garden care, utilities and maintenance within the home.
What are the annual costs of running a swimming pool, spa, home lift or other luxury features?
Costs vary according to energy use, servicing, water treatment, replacement parts and frequency of use. Estimate each feature separately in your upkeep budget.





